 13128872179
 2419493733
 Telegram:ukassignment021
ABF305 Investment Management
Lecture 11
Review the in-class test.
Cover the risk-return trade off:
Chapter 5 in the textbook, specifically pages 113-128 and pages 130-132.
Risk-return trade off.
风险收益权衡。
The risk return trade-off or relationship can be represented by an equilibrium.
可以表示为一个平衡的风险回报权衡关系。
Markowitz and Sharpe have addressed the risk-return relationship in modern portfolio theory.
马科维茨,夏普已经解决了现代投资组合理论中的风险与回报的关系。
Need measurements of:
The return of the asset.
The risk of an asset.
The quantitative trade-off between risk and expected return.
The return of an asset.
资产的回报
For stocks, the way to determine the rate of return, is from the dividend paid and also the capital gain or loss on the stock price.
对于股票来说,觉得资产回报的方法是来自已付股息和 股价上资本收益或亏损。
For example: If a stock costs $25 and after a year the price has changed to $27.80. In addition, you received a dividend of 40 cents for the stock at the end of the year. Then your percentage return is (27.80+0.40)-25 = (3.2/25) =12.8%
This percentage return or rate of return is denoted by the equation:
1+EAR = (1+ the holding period percentage return)^n
Where n = the number of holding periods in a year.
Effective annual return or EAR.
有效的年度回报率或EAR
If you do not hold the shares for 1 year, then you will need to adjust the return accordingly. Let us say that you bought a share for $18 and held it for 3 months after which the price was $19; you received no dividend. Your holding period percentage return for three months is determined as 19-18/18 = 0.0555 or 5.56%.
1+EAR = (1.0556)^4 = 1.2416 so the effective annual return is 24.16%.
The risk of an asset.
If risk is thought of in terms of the volatility of an asset’s returns, to quantify this risk, the return variance and standard deviation are employed. Specifically, variance and its square root which is known as the standard deviation, are the most commonly used measures of volatility. Remember volatility is unpredictability. The degree of movement of difference from an average return therefore represents a measure of just how unpredictable a return is.
How to calculate standard deviation.
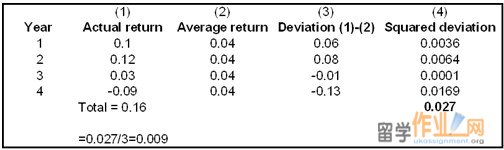
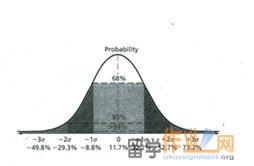
With an average return measure and standard deviation, employing a normal distribution which employs for these measures will tell you the probability of your return ending up in a given range.
Summary of what we know:
We can quantify return and risk for a single stock.
What about a portfolio?